| In brief
• Portugal’s first National Energy Storage Strategy targets 3 GW of battery storage by 2030 and 4.5 GW by 2040. • Two auctions allocate 1,050 MW of grid capacity: 750 MW for standalone storage and 300 MW for renewables with co-located storage. • Municipal revenue sharing and community benefit requirements are built into the auction design. • Hybrid projects such as Santa Marta and Baloiço stand to benefit from more predictable access to grid capacity. |
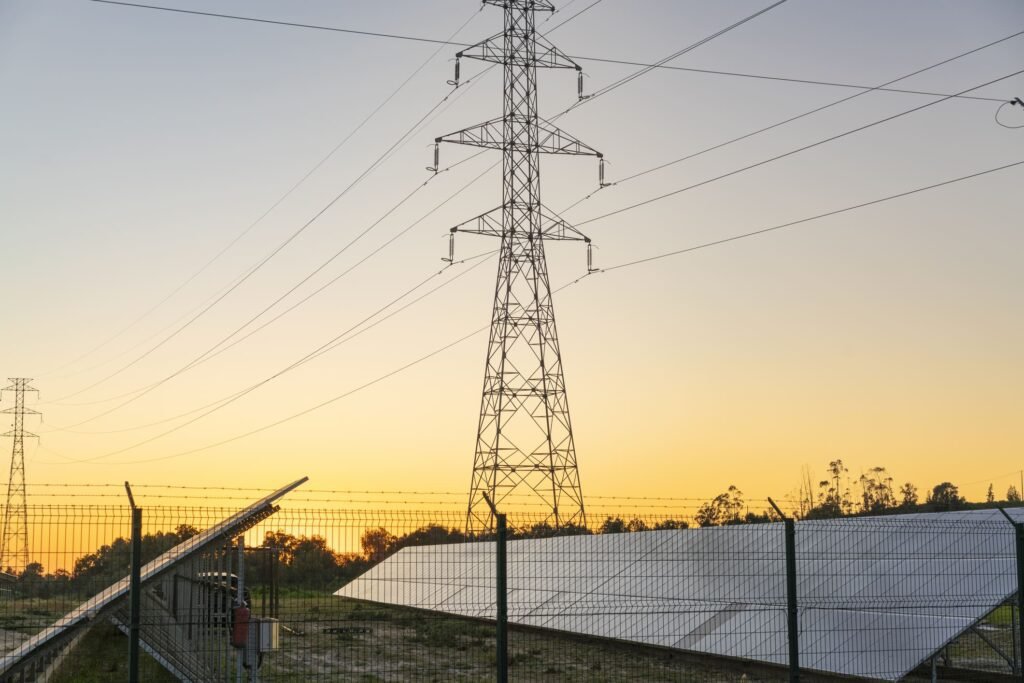
Portugal is undergoing a profound transformation of its electricity system, driven by accelerated renewable deployment and a decisive shift toward large-scale energy storage. In 2026, the Portuguese government introduced its first comprehensive National Energy Storage Strategy, which establishes long-term targets of 3 GW of battery storage by 2030 and 4.5 GW by 2040, alongside expanded pumped hydro capacity. These targets are grounded in technical studies conducted by INESC TEC and Instituto Superior Técnico, and they reflect a strategic recognition that storage is now essential to reduce curtailment, lower gas-fired generation, and ensure the efficient integration of Portugal’s rapidly growing solar and wind fleet. The government explicitly states that Portugal is entering a new phase in which the priority is not only installing renewable capacity but ensuring that this capacity is properly integrated into the grid through storage and flexibility mechanisms.
This strategic shift is reinforced by the launch of two major BESS auctions, scheduled for 14 September 2026, to allocate 1,050 MW of grid capacity. The first auction covers 750 MW of standalone battery storage, while the second allocates 300 MW of surplus grid capacity for renewable projects with co-located storage. These auctions introduce a permanent, recurring mechanism for allocating grid capacity to storage, providing developers with predictable access to injection points and reducing development risk. The regulatory design includes several innovations: municipalities will receive 30% of auction revenue (up to 70% for co-located projects), developers must allocate 2.5% of net income to local community benefits, and agrivoltaic projects receive a 20% bonus during the auction process. Minimum bid sizes, duration requirements, and strategic 400 kV nodes, such as Estremoz, Sines-Santo André, Abrantes, Pegões-Divor and Tavira, further structure the competitive landscape.
These reforms are occurring against the backdrop of Portugal achieving 80.7% renewable penetration in electricity generation in early 2026, the highest in the European Union. With more than 15 GW of solar projects under development and expected investments exceeding €10 billion by 2030, storage has become indispensable to maintain grid stability and reduce curtailment. The government’s Recovery and Resilience Plan (PRR) reinforces this trajectory, providing €99.75 million for at least 500 MW of storage capacity and an additional €60.25 million to strengthen the resilience of the Public Electricity Service Network (RESP) through grid-connected battery installations. The European Council’s approval of Portugal’s revised PRR in late 2025 secured €415 million for strategic investments in batteries, hydrogen, and grid reinforcement, extending execution deadlines to 2028/2029 and ensuring project viability.
Within this evolving national framework, the Santa Marta Solar Project and the Baloiço BESS Project are well positioned. Both projects benefit directly from the new auction mechanisms, which provide transparent and predictable access to grid capacity, an essential factor for reaching RTB (Ready-to-Build) status. The permanent auction scheme reduces regulatory uncertainty and enhances bankability, making the projects more attractive to institutional investors and bond buyers. The mandatory revenue-sharing mechanisms and community benefit contributions significantly strengthen local acceptance, reducing permitting friction and improving ESG performance. This is particularly relevant for Santa Marta, which is located in southern Portugal, where municipalities stand to gain substantial revenue from co-located storage projects.
The national shift toward hybridisation, combining solar, wind and storage, aligns closely with the design of Santa Marta, which is conceived as a large-scale hybrid renewable platform, and with Baloico, which forms part of a broader BESS pipeline. As Portugal moves toward a storage-enabled renewable system, hybrid projects gain a competitive advantage by reducing curtailment, improving dispatchability, and aligning generation with demand. The auction rules also create opportunities for both projects to secure strategic 400 kV nodes, benefit from agrivoltaic bonuses where applicable, and participate in the 300 MW co-located storage auction.
From a strategic perspective, Santa Marta and Baloiço exhibit strong alignment with national energy priorities. Their hybrid configuration matches future auction requirements, their local benefit mechanisms enhance social license, and their development timeline positions them as early movers in Portugal’s emerging storage market. While competition in the auctions will be intense and curtailment risks remain a factor, potentially reaching up to 1,100 hours for co-located projects under the auction design, the overall regulatory environment significantly enhances the projects’ bankability and long-term revenue stability.
In conclusion, Portugal’s 2026 energy reforms create one of Europe’s most attractive environments for hybrid renewable-plus-storage projects. The Santa Marta Solar Project and the Baloiço BESS Project stand to benefit substantially from national storage targets, permanent auction mechanisms, revenue-sharing frameworks, and priority grid-integration policies. These factors collectively strengthen the case for both projects as strategically aligned, future-proof infrastructure in one of Europe’s fastest-advancing renewable markets.
UNIVERE INVESTMENT SOLUTIONS | Access. Without the Noise.
Professional access only. Not for public or retail audiences. Univere Investment Solutions Limited is not authorised or regulated by the Financial Conduct Authority, and communicates this content in reliance on the relevant financial promotion exemptions under FSMA 2000. This content does not constitute financial advice or a personal recommendation. Capital is at risk. Investments may be illiquid and difficult to realise. Past performance is not indicative of future results. Prospective investors should seek independent financial and legal advice before making any investment decision.