A country running on one of Europe’s highest renewable shares still had to reprice its electricity because of a gas market thousands of miles away.
On 16 September 2026, Portugal’s energy regulator announced that the energy component of regulated electricity tariffs would rise from 1 October. The increase is small in absolute terms, five euros per megawatt hour, and it reaches a minority of consumers. The reason behind it is the part worth reading, because it describes a structural exposure that survives even in one of Europe’s most renewable power systems.
A country generating most of its power from its own sun, wind and water still repriced its electricity because of a gas market it does not control.
What the regulator actually did
ERSE, the Portuguese energy regulator, operates a quarterly adequacy mechanism. It compares the forecast cost of supply built into current tariffs against an updated estimate, and where the difference passes a defined threshold, a correction is triggered automatically. According to the regulator’s decision as reported on 16 September, the updated forecast showed a gap of 17.59 euros per megawatt hour against the figure underpinning tariffs through September. That breach triggered a five euro per megawatt hour correction to the energy component.
The practical effect is an estimated 2.7% increase on the average monthly bill for most regulated domestic customers, taking the expected annual price variation to 1.7% rather than the 1% originally forecast. The measure reaches around 779,000 customers, close to 4.6% of national electricity consumption, and almost all of them residential. Suppliers in the free market, where most Portuguese consumption sits, retain commercial autonomy and are under no obligation to pass the revision on.
The cause sits outside Portugal entirely
The regulator attributed the gap largely to rising natural gas prices connected to the conflict between Iran and the United States. That is the detail that matters for anyone thinking about energy infrastructure. Portugal did not have a bad month of sunshine or a domestic policy failure. A geopolitical event moved the international gas price, and a country with one of the highest renewable shares in the European Union still felt it in its regulated tariffs.
This is the same exposure we examined in what the Hormuz closure reveals about energy infrastructure. Imported fuel carries a route risk and a price risk that no domestic generation record fully removes, as long as the system still leans on that fuel at the margin.
The seasonal detail is the real lesson
The regulator noted that the impact of higher spot prices intensified during a period of seasonally lower renewable contribution. That single observation contains the whole argument for storage and firming.
Renewable output is not constant across a year. Hydro depends on rainfall, wind on weather patterns, solar on daylight hours that shorten through autumn. When the renewable share dips seasonally, the marginal unit of electricity is set by whatever fills the gap, and in Portugal as in most of Europe that remains gas. The price of that marginal unit then sets the wholesale outcome for everyone, regardless of how much clean power the system produced in aggregate over the year.
An average annual renewable share, however impressive, does not describe what happens in the hours when the resource is thin. That gap between the annual figure and the difficult hour is precisely what storage exists to close, and it is why generation alone has stopped being the interesting part of the investment case. We traced the same shift across a single week of Iberian news in four days in Iberian energy that told one story.
What this means for how capital reads the sector
There are two readings of a tariff rise like this one. The narrow reading treats it as a consumer story about bills. The wider reading treats it as a market telling you where its remaining vulnerability sits, which in this case is the hours when the renewable resource is weakest and the system reaches for imported gas.
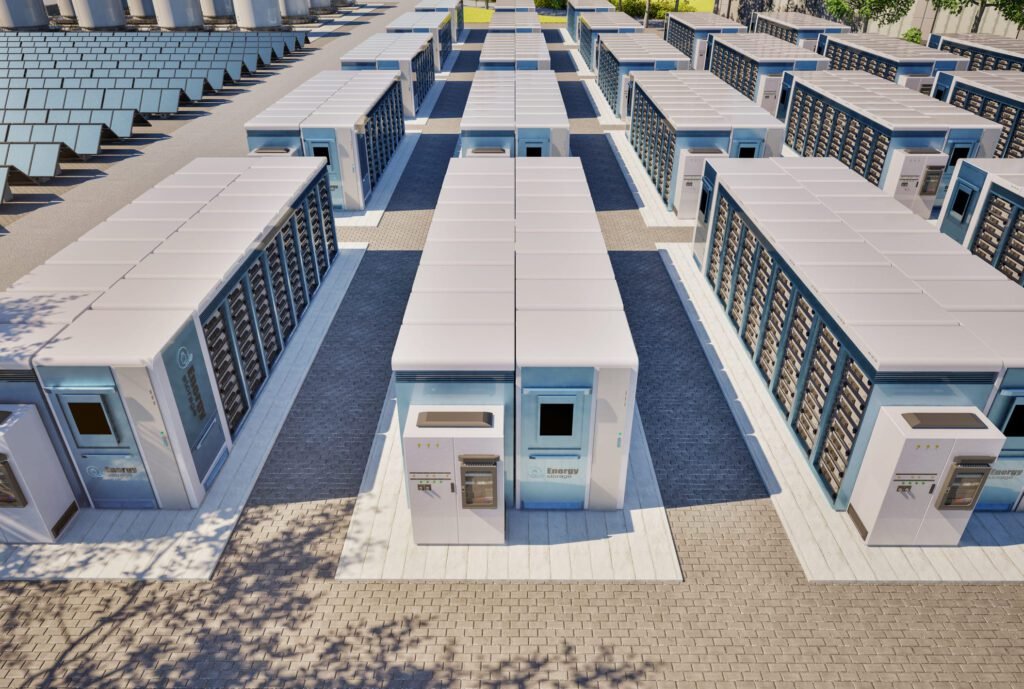
Assets that can fill that gap, storage, balancing capacity, interconnection, are being paid for something a solar panel on its own cannot provide. This is why the projects Univere introduces, including Solar45 and Baloico, pair generation with storage rather than treating the two as separate decisions. The reasoning behind that pairing is set out in solar and storage, the new default.
None of this makes any particular asset a good investment. A structural argument is not a forecast, infrastructure remains slow and exposed to policy and execution risk, and capital committed to it remains at risk. What the tariff decision provides is evidence, from a regulator rather than from a marketing deck, about where the system is still fragile.
Sources: ERSE decision as reported by energynews.pro, 16 September 2026.
UNIVERE INVESTMENT SOLUTIONS | Access. Without the Noise.
Professional access only. Not for public or retail audiences. Univere Investment Solutions Limited is not authorised or regulated by the Financial Conduct Authority, and communicates this content in reliance on the relevant financial promotion exemptions under FSMA 2000. This content does not constitute financial advice or a personal recommendation. Capital is at risk. Investments may be illiquid and difficult to realise. Past performance is not indicative of future results. Prospective investors should seek independent financial and legal advice before making any investment decision.